The End of Financial Year (EOFY) is always busy. Between finishing projects and managing cash flow, tax planning often gets pushed aside.
However, a short planning session before 30 June can significantly reduce your 2026 tax bill.
Below are five high-impact actions to consider.
1. Claim the $20,000 instant asset write-off
The government has officially extended the $20,000 instant asset write-off for the 2025–26 financial year. This is a massive win for small businesses with an annual turnover under $10 million.
- How it works: You can immediately deduct the full cost of eligible assets costing less than $20,000 each (net of GST if you’re registered).
- The Trap: The asset must be “first used or installed ready for use” by June 30. Simply paying the invoice isn’t enough; if that new delivery van or MacBook is still in the box on July 1, you can’t claim it this year.
- Tip: You can use this for multiple assets. If you buy three different tools at $15,000 each, you can claim the full $45,000 deduction this year.
2. Leverage the “12-Month Rule” for prepayments
Want to reduce this year’s taxable income? Prepay your expenses for the next year. Under the 12-month rule, small businesses can claim an immediate deduction for expenses that cover a period of up to 12 months.
Common prepayments include:
- Business insurance premiums.
- Rent for your office or warehouse.
- Professional subscriptions and software (Xero, Adobe, industry bodies).
- Utility bills or interest on business loans.
3. The “June 20” Superannuation Deadline
The June quarter superannuation guarantee (SG) is legally due by 28 July.
However super is only tax deductible in the financial year the fund receives the contribution.
If you pay in July, the deduction falls into 2026–27.
Tally Ho Recommendation: We suggest clearing your super payments by June 20. This allows enough time for clearing houses and banks to process the transfer so the money “lands” in the employee’s fund before the June 30 cutoff.
4. Conduct a “Spring Clean” of Your Ledgers
Don’t pay tax on money you’re never going to see. Before June 30, sit down and review your receivables and inventory.
- Bad Debts: If a customer debt is unrecoverable and has previously been included in your assessable income, formally write it off in your accounting records before 30 June. This allows you to claim a tax deduction for the amount written off.
- Stock-Take: If you have inventory that is damaged, expired, or unsellable, consider writing it down to market selling value or replacement value. A lower closing stock value directly reduces your taxable profit.
5. Top up your Personal Super (Concessional Cap)
For the 2025–26 year, the concessional contributions cap is $30,000. This includes the super your business pays for you plus any personal contributions you make.
If you’ve had a profitable year, making a personal contribution to your super and claiming a tax deduction is one of the most effective ways to build personal wealth while lowering your business tax bill.
Note: Ensure you lodge a “Notice of Intent to Claim” with your fund!
Your EOFY “Quick Action” Checklist
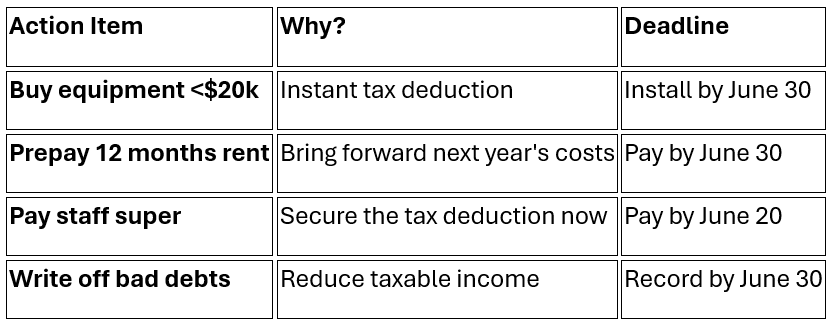
Ready to finish the year strong?
Don’t leave your tax return to chance. At Tally Ho Accounting, we help Sydney business owners find the “hidden” deductions that DIY tax lodgers often miss.
Would you like us to run a “Pre-June 30 Tax Projections” session for your business?
|
Need help right now? Contact Tally Ho Accounting today. Phone: 0451 637 848 Email: [email protected] |
Disclaimer: This blog is for general information purposes only and does not constitute legal or tax advice. DPNs are complex legal matters; please contact us for advice specific to your situation.